LOS vs Loan Management System vs Core Banking: What a Kenyan Lender Actually Needs
Loan origination system, loan management system or core banking? What each does, how they connect, and which combination suits Kenyan banks, SACCOs and lenders.
Short answer: A loan origination system (LOS) decides whether a loan should be made and records who approved it; a loan management system (LMS) runs the loan after it is made, from repayment schedule to arrears and collections; a core banking system holds the customer, the accounts and the general ledger, usually including loan accounts. Most Kenyan banks run core banking plus an LOS, many SACCOs run a SACCO core system and add an LOS only when approvals get complicated, and credit-only lenders often run a single all-in-one LMS.
This guide is for heads of credit, CIOs, operations managers and procurement teams at Kenyan banks, microfinance banks, SACCOs and non-deposit-taking lenders who keep meeting all three terms in vendor conversations and want to know which one they are actually short of. Vendors use the words loosely, and "loan management system Kenya" searches return products that do very different jobs.
Creodata sells loan origination software, not a loan management system or a core banking system, so we say plainly where that line sits. The definitions below apply to any vendor.
What is a loan origination system?
A loan origination system runs the credit decision. It takes an application in, gathers the documents and checks, routes the proposal to the people who must review and approve it, and records every decision with who made it and when. Its job ends when an approved, documented loan is handed over to be booked and disbursed.
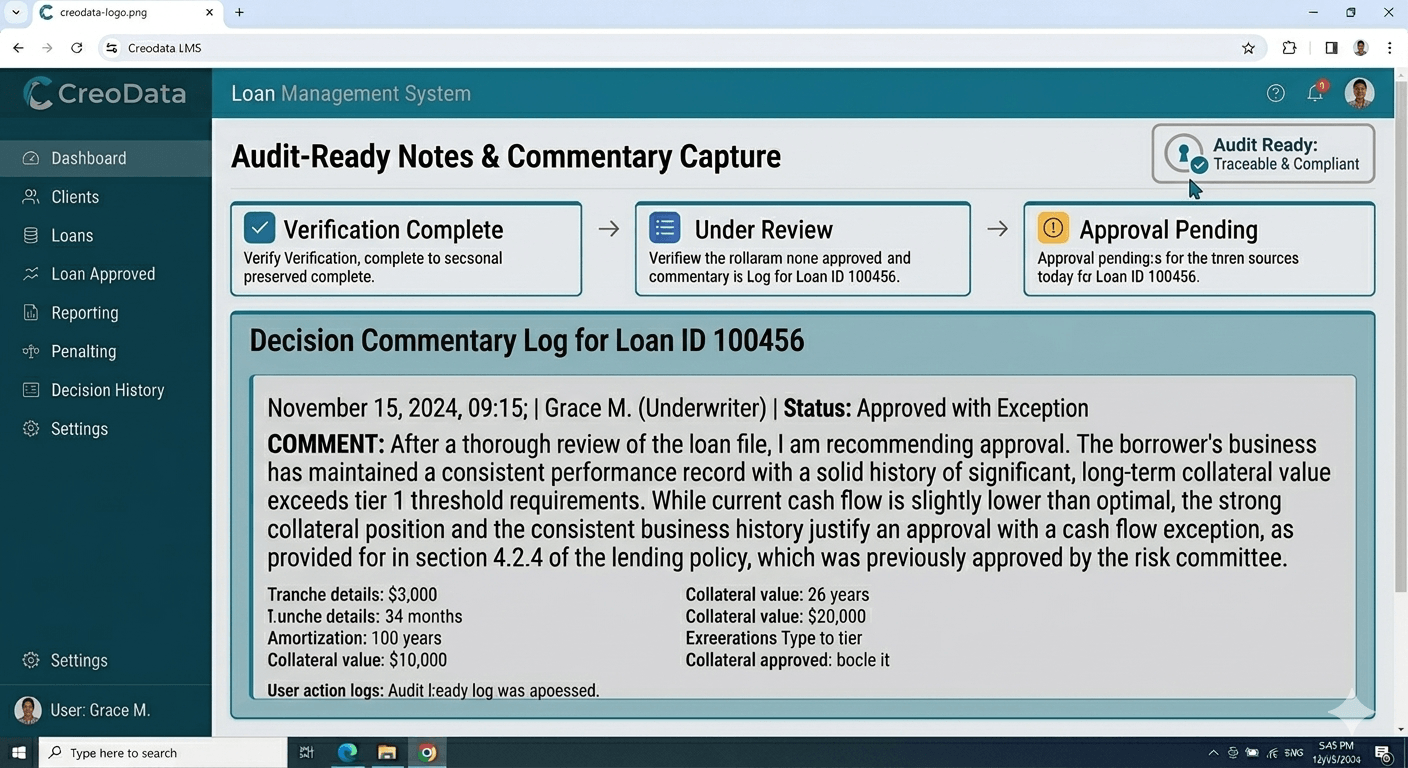
The important words are decide and record. A good LOS knows your approval rules: which officer can approve what amount, which applications must go to a branch or management credit committee, when legal and risk must sign off. It keeps the audit trail an internal auditor or examiner will ask for. It does not usually calculate the next instalment or chase an overdue one.
What is a loan management system?
"Loan management system" is used in two ways in Kenya, which is the root of most confusion.
In the narrow sense, an LMS is loan servicing software. Once a loan is booked it generates the repayment schedule, accrues interest, posts repayments, applies penalties, ages arrears, and drives reminders and collections. That is the ledger side of lending.
In the broad sense, especially among digital lenders and smaller credit providers, "loan management system" means an all-in-one platform that does light origination (an application form, a scoring rule, a single approver) plus full servicing, sometimes with its own accounting. Many products sold as "loan management system Kenya" are this kind.
When a vendor says LMS, ask which half it is strong in. A platform that is excellent at schedules and collections may have a one-step approval, and one that is excellent at committee routing may not service loans at all.
What is a core banking system?
A core banking system is the institution's system of record. It holds customer information files, deposit and current accounts, the general ledger, payments, and in most banks the loan accounts themselves, with their schedules and interest accrual. A SACCO core system plays the same role for a SACCO, usually split into the back-office savings and loans side (BOSA) and the front-office, withdrawable-account side (FOSA).
Because the core already holds loan accounts, a bank rarely needs a separate servicing LMS. What the core does not usually do well is the human workflow before a loan exists: the proposal, the document chase, the committee pack, the conditions and the approvals.
LOS vs LMS vs core banking: side by side
| Loan origination system (LOS) | Loan management system (LMS, servicing) | Core banking / SACCO core | |
|---|---|---|---|
| Purpose | Decide and document whether to lend | Run the loan after it is made | Hold customers, accounts and the ledger |
| Main users | Relationship managers, credit analysts, credit admin, committees, legal, risk | Loan operations, collections, finance | Tellers, operations, finance, every department |
| Key functions | Intake, document checks, appraisal, amount-based approval routing, conditions, audit trail, handover to booking | Schedules, interest accrual, repayment posting, penalties, arrears ageing, collections | Customer records, deposits, payments, general ledger, loan accounts, regulatory returns |
| Data it owns | The application, the credit decision and who made it | The loan's repayment history and arrears status | Customer master, account balances, accounting entries |
| Who typically buys it in Kenya | Banks and microfinance banks with credit committees; larger SACCOs with multi-level approvals | Credit-only and digital lenders, smaller MFIs, some SACCOs | Every bank, microfinance bank and deposit-taking SACCO |
| Provider types | Global LOS suites, workflow-first LOS vendors, origination modules of core-banking vendors | Local loan-management and SACCO system vendors, digital-lending platforms | International core-banking vendors, regional and local core and SACCO system vendors |
The table is a generalisation. Some core and SACCO systems have usable approval steps, so test each product against your own process.
How the three systems connect
In an institution that runs all three pieces, a loan's life looks like this:
- Application. The customer applies at a branch, through a relationship manager or through a digital channel. The LOS creates the application record.
- Checks and appraisal. Documents are collected and verified, identity and credit bureau checks are run, and the credit analyst assesses affordability and risk. Results attach to the application in the LOS.
- Approval. The LOS routes the proposal by amount and product to the right approvers and committees, and records each decision.
- Booking. The approved loan is created as a loan account in core banking (or in the LMS, for a lender without a core). Limits are marked and fees set up.
- Disbursement. Funds are released from the core, ideally under maker-checker control.
- Servicing. Repayments, interest, arrears and collections run in the core or the LMS for the life of the loan.
The handoffs are where projects succeed or fail. The LOS needs customer data from the core at intake (so it does not create a duplicate customer), and it must pass a clean, complete booking instruction back after approval. The core then needs to tell the LOS that the loan was booked and disbursed, so the application closes with a full record.
Well-built integrations use an API or a message bus rather than file drops. A message bus (the queue that carries "loan approved" and "loan booked" events between systems) means one system can be briefly unavailable without losing an instruction, and every message can be traced. Our guide to loan origination system integration with core banking shows this pattern, and loan booking and disbursement in core banking covers the booking step in detail.
Which combination suits your institution?
Commercial bank: core banking plus an LOS
A bank already services loans in its core. What it usually lacks is a controlled route from proposal to approval across branches, credit, committees, legal and risk. Adding a loan origination system on top of the core, integrated for customer data and booking, is the common pattern. Buying a separate servicing LMS would duplicate what the core already does.
Microfinance bank: core banking plus, often, an LOS
Microfinance banks are licensed and supervised by the Central Bank of Kenya under the Microfinance Act, 2006, and run a core system for deposits and loans. Whether they also need an LOS depends on the loan book. High volumes of small, similar group or individual loans can often be approved inside the core. Growing SME or larger individual lending, with credit committee approvals, is where a separate origination workflow starts to pay its way.
Deposit-taking SACCO: SACCO core plus an optional LOS
Deposit-taking SACCOs are licensed and supervised by SASRA under the Sacco Societies Act, 2008. Their SACCO core system handles members, shares and deposits (BOSA), front-office accounts (FOSA) and loan accounts. Many SACCOs appraise loans inside that system. An LOS earns a place when the approval path becomes multi-level (credit officer, credit committee, board for large or insider loans), when guarantor and security checks need to be traceable, or when branches need their own queues and limits. Our guide to SACCO loan origination software in Kenya covers that case.
Credit-only or digital lender: often an all-in-one LMS
Non-deposit-taking credit providers have no deposit ledger to protect, so a single platform that originates, disburses, services and collects is usually the simplest fit. Their regulatory position has also changed: the Business Laws (Amendment) Act, 2024 extended CBK licensing to all non-deposit-taking credit providers, and CBK published implementing regulations in draft in August 2025. Our guide to CBK digital lending compliance software covers what that means for systems. A credit-only lender that moves into larger, committee-approved loans may later add an LOS in front of its LMS.
Payroll or check-off lender: core plus check-off origination
Check-off lending, where repayments are deducted from salary, needs origination steps that a generic LOS does not have: payslip affordability, employer scheme rules, and for government payrolls, deduction data from the Integrated Personnel and Payroll Database (IPPD). The Employment Act, 2007 limits total deductions to two-thirds of wages, so the affordability check has to see every existing deduction. Servicing still sits in the core. Creodata's Workplace Banking Application is built for this case, with IPRS, CRB, KRA and Finacle integrations. Check-off loans in Kenya explains how the deductions work.
Signals you need a loan origination system
You probably need an LOS, rather than more features in your core or LMS, when:
- Approvals involve committees. Proposals go to a branch credit committee, a management credit committee or the board, and packs are assembled by email or printed.
- You operate across many branches. Each office needs its own queue and approval limits, and head office cannot see where a file is.
- Audit keeps finding the same gaps. Missing sign-offs, approvals above an officer's limit, or no record of who changed a condition.
- Customers and relationship managers complain about turnaround. Nobody can say which stage a loan is stuck in or for how long.
- Credit policy changes take a software release. New products, fees or approval limits need vendor work instead of configuration.
Common mistakes
Buying an LMS and expecting committee workflow. A servicing-strong LMS may offer "approval" as a single status change. If your credit policy needs branch and management committees, legal and risk sign-off, test that path end to end in a demo before you sign.
Rebuilding servicing inside the LOS. Some projects try to make the origination system calculate schedules or track repayments "for visibility". That creates two versions of the loan balance. Let the core or the LMS own servicing, and feed the LOS the status it needs.
Skipping the integration design. Deciding which system owns the customer record, the loan account and the approval record should come before choosing the vendor, not after.
Comparing products of different types on one checklist. An LOS, an LMS and a core system will all score badly on each other's requirements. Decide which gap you are filling first. Our loan origination RFP checklist and its scoring workbook are built for the origination layer.
Where Creodata fits
Creodata's loan origination system is the origination layer only. It runs the credit workflow for any loan product through 13 role-gated stages, from application intake to final disbursement, with amount-based routing through business credit committee (BCC), head of business, management credit committee, committee and risk gates. Every stage has an SLA timer, every decision is logged with actor and timestamp, and queues and approval limits are scoped per office. It is designed to integrate with your core banking system over a message bus, and it runs on Microsoft Azure or on-premises.
It does not service loans. Repayment schedules, interest accrual, collections and the ledger stay in your core banking or SACCO system. For payroll lending, the Workplace Banking Application adds check-off origination with IPRS, CRB, KRA, Comply Advantage and Finacle integrations and maker-checker on booking and disbursement. Pricing is quoted per institution. For the full evaluation, see the loan origination software buyer's guide for Kenya and our guide to credit approval workflows in Kenyan banks.
Frequently asked questions
What is the difference between a loan origination system and a loan management system?
A loan origination system handles everything up to the credit decision and its handover: application, documents, appraisal, approval routing and the audit trail. A loan management system, in the servicing sense, handles everything after the loan is booked: schedules, interest, repayments, arrears and collections. Some products marketed as loan management systems in Kenya do both, usually with lighter origination.
Do banks in Kenya need an LOS if they already have core banking?
Not always, but most banks with credit committees find their core system's origination features too thin. The core already services loans well; what an LOS adds is controlled routing through committees, legal and risk, per-stage tracking and an approval record an examiner can follow. The two are integrated so the approved loan is booked in the core without re-keying.
What is the best loan management system for a SACCO in Kenya?
Start with the SACCO core system, since it holds member accounts, BOSA and FOSA, and loan accounts. Most SACCO loan processing can run there. Look at an additional loan origination system if your approvals are multi-level, if guarantor and security checks need a clear trail, or if branches need separate queues. Compare SACCO systems and LOS products against your own loan approval process, not a generic feature list.
Can one system do origination, servicing and core banking?
Some platforms aim to, particularly for credit-only lenders without deposits. For banks, microfinance banks and deposit-taking SACCOs, the core system is usually the regulated system of record, and the realistic choice is between using its origination features or adding a specialist LOS.
How does an LOS integrate with core banking?
Typically through APIs or a message bus. The LOS reads customer data from the core at intake, and after approval it sends a booking instruction; the core confirms booking and disbursement back. Message-based integration lets each side tolerate the other being briefly unavailable, and each message can be traced for audit. Ask vendors to show this with your core system.
Is loan origination software the same as a digital lending platform?
No. A digital lending platform usually combines a customer-facing channel, automated decisioning and servicing for high-volume, small-value loans. Loan origination software is aimed at loans that need people to review and approve them, such as SME, corporate, mortgage and larger personal loans. Some lenders run both, for different products.
See how Creodata's loan origination software fits alongside your core system in a demo, or score vendors with the free loan origination RFP checklist.