Loan Origination Software in Tanzania: A Buyer's Guide for Banks, SACCOS and Microfinance Lenders (2026)
How to choose loan origination software in Tanzania: who needs one under BoT, evaluation criteria, provider types, cost drivers and red flags.
Short answer: Loan origination software (LOS) runs a loan from application to disbursement: intake, documents, identity and bureau checks, appraisal, committee approval and hand-off to the loan management or core system that books and services the loan. Choose one by scripting demos on your own products and approval matrix, testing the Tanzanian checks and integrations you need, and comparing three-year costs.
This guide is for credit, IT and procurement teams at Tanzanian banks and financial institutions, microfinance institutions, credit companies, money lenders, digital lenders and SACCOS replacing paper files, email approvals or an older system. Searches for "loan management system Tanzania", "SACCOS software Tanzania" or "digital lending software Tanzania" return very different kinds of product, so it pays to know which kind you are looking at.
Creodata sells loan origination software in Tanzania, so we say plainly where we fit near the end. The criteria before that are the ones we would use to choose any vendor. This is a practical guide, not legal advice: confirm requirements against current law and your regulator's guidance.
What does a loan origination system do?
A loan origination system is the workflow layer for credit decisions. It collects the application, makes sure the right documents and checks are in place, routes the file to the people with authority to approve it, and passes an approved loan to your core banking, SACCOS or loan management system.
| Function | What it does | What matters in Tanzania |
|---|---|---|
| Application intake | Captures applicant, product and loan details | Forms for salary, SME, agricultural, asset-finance and group loans |
| Documents | Collects and verifies each product's documents | National ID, payslips or statements, title deeds, vehicle registration cards |
| Checks | Records identity, bureau and sanctions results | NIDA national ID, reports from the licensed bureaus, sanctions and PEP screening |
| Appraisal | Builds the credit proposal and affordability view | Cash flow for SME and agricultural loans; fee disclosure for digital products |
| Approval | Routes each file by amount, product and office | Branch and management committees, the board or SACCOS loans committee, risk sign-off |
| Fulfilment | Security, conditions precedent and release | Maker-checker before funds leave; charge documents and insurance evidence |
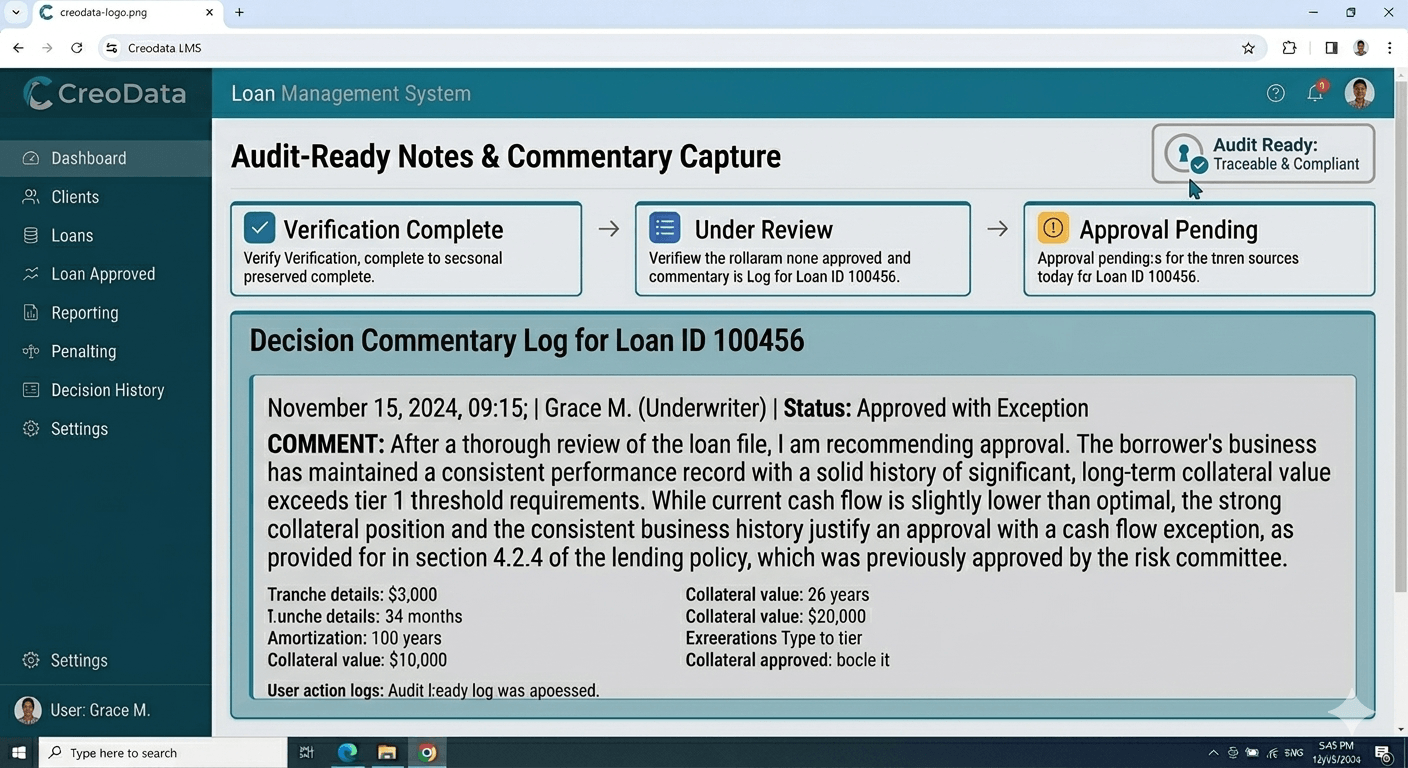
| Evidence | Records every decision and timestamp | An audit trail for internal audit and the Bank of Tanzania |
An LOS usually does not service the loan. Repayment schedules, accrual, collections and the ledger normally stay in the core banking or SACCOS system. Some products sold as a "loan management system" do both; many do only one well. Our explainer on LOS vs loan management system vs core banking sets out the boundary.
Who needs loan origination software in Tanzania?
Any lender whose approvals involve several people, branches or products soon outgrows spreadsheets and email. Where you sit in Tanzania's framework shapes what an examiner asks of a loan file:
- Banks and financial institutions. The Bank of Tanzania (BoT) licenses and supervises them under the Banking and Financial Institutions Act 2006.
- Microfinance lenders. The Microfinance Act 2018 sets four tiers: Tier 1 deposit-taking microfinance institutions; Tier 2 non-deposit-taking microfinance service providers (credit companies, individual money lenders and digital lenders); Tier 3 SACCOS; and Tier 4 community microfinance groups. BoT licenses Tiers 1 and 2.
- Tier 2 and digital lenders. Tier 2 providers fall under the Microfinance (Non-Deposit Taking Microfinance Service Providers) Regulations 2019 (GN 679 of 2019). A 2025 draft to replace them has been published but we have not found it gazetted, so work to the 2019 Regulations. In 2024 BoT moved against 69 unlicensed digital lending apps, and it has issued guidance for Tier 2 digital lenders covering fee disclosure, ethical debt collection, data privacy and complaints handling. BoT publishes a list of approved lenders, so check your partners' status.
- SACCOS. SACCOS are Tier 3, with their own regulations (GN 675 of 2019). Confirm which authority supervises your SACCOS day to day. SACCOS lending leans on member savings, guarantors and committee approval, which is where a workflow helps most.
All lenders are bound by the Personal Data Protection Act 2022, in force since 1 May 2023. Data controllers and processors must register with the Personal Data Protection Commission (PDPC), renewing every five years.
None of these laws tells you to buy software. They do make evidence of who approved what, on which documents and within which limit, something you must produce quickly.
The Tanzanian checks and integrations that shape the choice
Most demos look alike until you test them against the checks your credit policy requires:
- National ID. The National Identification Authority (NIDA) issues the national ID. Ask how the vendor verifies an ID (directly, through an intermediary or manually), how the result is stored with the file, and what happens when the service is down.
- Credit bureau reports. BoT licenses credit reference bureaus, and there are two: Creditinfo Tanzania and Dun & Bradstreet Credit Bureau Tanzania. Ask how reports are stored with each application and whether a product can require both.
- Sanctions and PEP screening of borrowers and guarantors, natively or by calling your AML system.
- Core banking or SACCOS system integration so approved loans are booked without re-keying; see LOS integration with core banking.
- Disclosure evidence for digital and Tier 2 products: the fees and terms shown to each borrower, and how complaints are recorded.
For committee and risk-gate design, credit approval workflows in Kenyan banks carries over directly to Tanzanian banks and larger microfinance lenders.
Evaluation criteria for loan origination software in Tanzania
Weight these before the first demo, and score every vendor against them.
| Criterion | What to test |
|---|---|
| Workflow configurability | Administrators change a product's stages without code, with changes versioned and approved |
| Approval matrix | Routing by amount, product, risk grade and office; limits changed under maker-checker |
| Document requirements | A missing mandatory document blocks progress; who verified each document, and when |
| Tanzanian checks | NIDA ID, reports from both bureaus and sanctions/PEP: live in Tanzania, planned, or to be built |
| Core or SACCOS integration | Automatic booking and disbursement; how failed postings are reconciled |
| Disclosure and pricing | Rates and fees per product, shown consistently to the borrower |
| SLA visibility | A timer on every stage, escalation on breach, a live pipeline by branch and officer |
| Audit trail and RBAC | An append-only log no administrator can edit; access scoped by role, branch and limit |
| Data protection and hosting | Where data, backups and support access sit; an on-premises option if data must stay in Tanzania |
| Local support | A named team, support in East Africa Time, references in Tanzania or the region |
| Three-year cost and exit | Every cost line itemised on your volumes; loan files and audit history returned in open formats |
The types of loan origination software provider in Tanzania
Providers of loan origination and loan management software in Tanzania fall into several types. Knowing which you are talking to tells you what to test.
| Provider type | Typical strengths | Watch for |
|---|---|---|
| Global LOS suites | Depth, configurability, large-bank references | Cost, implementation effort, and whether NIDA and bureau checks work natively or through partners |
| Core-banking add-on modules | Tight integration with the vendor's own core | Workflow depth, and lock-in to one core platform |
| Local SACCOS and microfinance systems | Local presence, member data and servicing in one place | Committee routing, multi-level approvals and audit depth for larger loans |
| Digital-lending platforms | High-volume automated decisions | Fit for committee-approved, document-heavy SME, agricultural or secured loans |
| Workflow-first LOS | Configurable stages, approval matrices, SLAs and audit trail | Servicing stays in your core, so integration quality is critical |
These can be combined: a workflow-first LOS for committee-approved lending and a digital platform for small instant loans, both booking into one core.
Questions to ask in demos
Send every shortlisted vendor the same script, built on your own products, in advance:
- Configure a product with its document checklist and approval route while you watch.
- Route three applications of rising amounts to branch committee, management committee and board. What happens if the amount changes after approval?
- Block a self-approval: one user capturing and approving the same file.
- Show the NIDA and bureau results stored with the file, and what happens when one is missing.
- Book into core in a test environment and reconcile a failed posting.
- Breach an SLA and show who is alerted.
- Produce the evidence for a past approval: every decision, document version and approver.
Call two comparable references and ask what went wrong, not only what went right.
What drives the cost of an LOS in Tanzania
Vendors price differently, so ask each to itemise the same lines over three years:
- Licence model: per user, branch, loan volume or module, or an enterprise fee.
- Integrations: often priced one by one; bureau and ID checks carry their own fees.
- Implementation: configuration, workflow design, migration and training, plus travel if the team is based outside Tanzania.
- Hosting: cloud subscription, or servers and operations on-premises.
- Support and change requests: whether new products are configuration you do or changes you pay for.
- Currency: US dollars or Tanzanian shillings, and who carries the exchange-rate risk.
A low licence fee can hide higher integration and change-request costs; compare three-year totals.
Red flags
- The demo only uses the vendor's sample products.
- Changing a stage or approval limit needs the vendor's developers.
- An administrator can edit or delete audit entries.
- "Integrated with NIDA and the bureaus" turns out to be a roadmap item or another country's integration.
- Answers about where your data sits are vague or change between meetings.
- "Loan management" means servicing only, with approvals still on email.
Use the free RFP workbook
The loan origination system RFP checklist and scoring template (Excel, 25 KB) holds 50 requirements in nine areas, each with a priority, a question, the evidence to request and a 0–5 score for up to three vendors. It was written for Kenya, so adapt the Kenyan integration rows (IPRS, KRA, IPPD) to NIDA, the two Tanzanian bureaus and your core system; the workflow, audit, hosting and commercial rows carry over. The guide to the checklist explains how to use it, and our loan origination software buyer's guide for Kenya covers the Kenyan edition for groups lending in both countries.
Where Creodata fits
Creodata is a Nairobi software company, and our loan origination system is a workflow-first LOS for lenders whose loans pass through credit committees and multi-level approvals. Tanzanian lenders get the same software as Kenyan ones, configured per institution. It runs a 13-stage, role-gated workflow from application intake to final disbursement, routes each application by amount through credit committees, Board and risk gates (re-checking the amount at every decision, with configurable limits), times every stage against an SLA, and records every decision, assignment and document action in an audit trail. Products, fees, collateral, required documents and routing rules are configured without code, with approval limits per office.
It has no built-in NIDA or credit bureau integration. An ID verification result and a report from Creditinfo Tanzania or Dun & Bradstreet Credit Bureau Tanzania can be made required documents for any product, checked before the file reaches a credit decision; direct integrations are scoped per institution. The IPRS, CRB and KRA integrations in our Workplace Banking Application are Kenya-only. It is not a loan servicing platform, a mobile lending platform or a scoring engine: servicing stays in your loan management, SACCOS or core banking system.
It runs on Microsoft Azure or on-premises on Kubernetes with the same features. If borrower data must stay in Tanzania, the on-premises edition keeps it in your own data centre. Pricing is quoted per institution. See how the requirements map to loan origination software in Tanzania; if you are also reviewing AML, see our AML compliance software buyer's guide for Tanzania. To shortlist us, book a demo and bring your own products and approval matrix.
Frequently asked questions
What is the best loan origination software in Tanzania?
There is no single best system, only the best fit for your products, approvals and core system. Shortlist two or three vendors that meet your Must-have requirements, run the same scripted demo on your own products, and score them with a weighted checklist such as our LOS RFP checklist.
What is the difference between a loan origination system and a loan management system?
A loan origination system handles everything up to disbursement. A loan management system usually means servicing afterwards: schedules, repayments, accrual and collections. In Tanzania the terms are often used interchangeably, so ask each vendor which stages it covers.
Which lenders does the Bank of Tanzania license?
BoT licenses banks and financial institutions under the Banking and Financial Institutions Act 2006. Under the Microfinance Act 2018 it licenses Tier 1 deposit-taking microfinance institutions and Tier 2 non-deposit-taking providers: credit companies, individual money lenders and digital lenders. SACCOS are Tier 3 and community microfinance groups Tier 4.
Do SACCOS in Tanzania need loan origination software?
No law requires it, but many benefit. SACCOS loans involve guarantors and committee approvals, and a SACCOS needs evidence of how each loan was approved. A small SACCOS may manage with its SACCOS system's loan module; one with several branches usually needs a proper workflow.
Which credit bureaus operate in Tanzania?
As far as we could find, BoT has licensed two: Creditinfo Tanzania and Dun & Bradstreet Credit Bureau Tanzania. Your LOS should store each report with the application and let you require one or both for a product.
Should an LOS be hosted in the cloud or on-premises in Tanzania?
Either can work. Cloud is quicker to start; on-premises keeps borrower data in your own data centre. Weigh the Personal Data Protection Act 2022 and your regulator's expectations on outsourcing, and ask where production data, backups and support access sit.
See how Creodata's loan origination software in Tanzania meets these criteria in a demo, or score every shortlisted vendor with the free LOS RFP checklist.