The Corporate Account Opening Process, Step by Step
The corporate account opening process step by step — from business information and account selection through compliance, signatories, board resolution, documents, review, and account creation.
Opening a corporate or business bank account is a two-sided process. The applicant supplies a structured set of information and documents, and the bank runs that submission through a controlled chain of checks before an account number is ever issued. When the two sides are out of step — a missing CR12, an ambiguous signing mandate, a beneficial owner who was never disclosed — the application stalls, and neither party can see where. This guide walks the full journey the way both sides actually experience it: the applicant-facing steps in order, and the bank workflow that runs behind each one.
For the wider strategic picture, see the complete guide to business account opening. This article stays close to the mechanics of a single application, mirroring the nine-step wizard and the staff review workflow in the Creodata Bank Account Opening System.
The applicant journey: nine structured steps
A corporate application is not one long form; it is a sequence of decisions, each of which narrows what comes next. Creodata BAOS presents this as a nine-step wizard that maps directly onto a bank's account-opening form and auto-saves to draft between steps, so an applicant can leave and return without losing progress. Walking the steps in order shows why the sequence matters.
Step 1 — Business information. The application begins with the entity itself: company name and registration or business type, KRA PIN, date of incorporation, the nature of the industry and key activities, employee range, annual turnover range, the purpose of the account, and the mailing and physical addresses. Primary and alternative contacts are captured here too. This is the foundation that compliance and risk assessment later build on, which is why it comes first.
Step 2 — Account selection. The applicant chooses the account product or type, the currency — Kenyan shillings or a foreign currency — and the customer segment. Segment matters internally because many banks use it to decide which branch and which team handle the application.
Step 3 — Account facilities. Here the applicant selects the services the account will carry: a debit card, cheque book, mobile and internet banking, e-statements, and transaction alerts. Some of these selections have downstream consequences — notably, they govern whether the Lipa Na M-PESA step appears later.
Step 4 — Compliance. This is where the application declares its risk posture: the PEP (politically exposed person) declaration, the FATCA declaration, and the significant stakeholders — the beneficial owners, whether directors, shareholders, partners, or a sole proprietor. Getting this right at source avoids costly rework, and it is worth understanding the beneficial ownership and significant stakeholder requirements before completing it.
Step 5 — Authorised signatories. Up to four signatories are captured, each with identification and a passport photo. Signatories and the mandate that governs them are a frequent source of delay, which the guide to authorised signatories and signing mandates covers in depth.
Step 6 — Signing mandate. The operating instruction is set here: singly, jointly by all, jointly by any two, three, or four, either-or-survivor, or a special arrangement. Terms-and-conditions acceptance is recorded at this step.
Step 7 — Lipa Na M-PESA short code. Conditional on the facilities chosen in step 3, this step handles a paybill or till short-code application for businesses that need to collect payments through M-PESA. Applicants who did not select the relevant facilities never see it.
Step 8 — Board resolution. For a company, the board must authorise the opening of the account and the operation of it. This step captures the resolution items, the authorised officials, and daily limits. The board resolution for a company bank account explains what a bank looks for here.
Step 9 — Documents and review. The final step is a checklist-driven upload of supporting documents followed by a review of the whole application before submission. The Kenya document checklist sets out what is typically required, from the Certificate of Incorporation and CR12 to the KRA PIN certificate and the board resolution itself.
Because the wizard auto-saves, an incomplete application can be resumed later from the customer self-service portal, and the applicant tracks status through a non-enumerable reference token rather than a guessable sequential number.
What the bank does behind each step
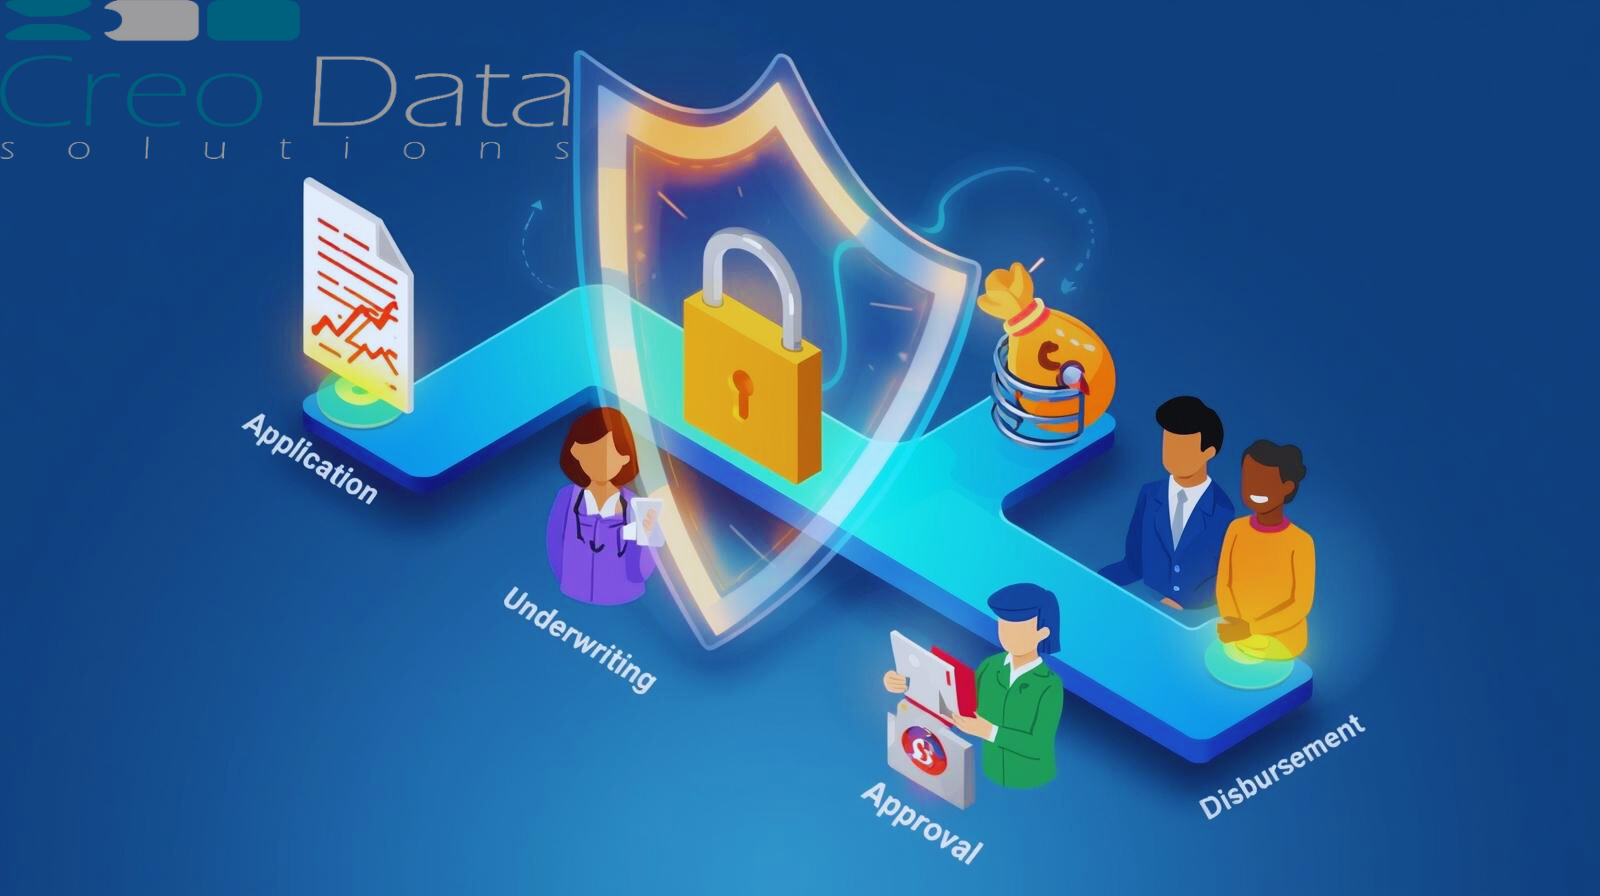
The applicant sees nine steps. Behind them, most banks run a six-stage workflow that begins the moment the application is submitted.
The first stage, Submission, simply registers the completed application and starts the clock. Compliance check then screens the people named in the application against sanctions and PEP lists, alongside the declarations made in step 4, and puts a compliance officer in the loop. Document verification confirms that every item on the checklist from step 9 is present and legible, and flags anything missing or inconsistent. Internal review is the staff assessment of the application as a whole. Approval is the decision point. Finally, Account creation is the point at which the approved application becomes an account on the bank's core systems.
In Creodata BAOS, a reviewer claims the application from the unassigned queue, verifies documents — one at a time or the whole application at once — and approves or rejects it (or emails the applicant for more information); once the core banking system opens the account, staff record the account number in BAOS. SLA timers run on the workflow steps and a dashboard shows average time per step, and branch-scoped roles mean a reviewer at a branch sees only that branch's applications. BAOS works out every person who needs screening — directors, beneficial owners, signatories — once each, and lists them on the application for your compliance team; the screening itself runs in your screening tool.
Throughout, applicants get an email at each key step, and every workflow action is recorded with who did it, in which role, when and from which address and device. The compliance and review work draws on the deeper disciplines covered in customer due diligence for business accounts and KYB — know your business — explained.
Mapping applicant steps to bank workflow stages
The two sides do not line up one-to-one. Several applicant steps feed a single workflow stage, and some stages draw on the whole application at once. The table below shows where the information captured in the wizard is exercised in the bank workflow.
| Applicant step | Primary bank workflow stage |
|---|---|
| 1. Business information | Submission; basis for Compliance check and Internal review |
| 2. Account selection | Submission; routing to branch and segment |
| 3. Account facilities | Internal review; drives Lipa Na M-PESA handling |
| 4. Compliance (PEP, FATCA, stakeholders) | Compliance check |
| 5. Authorised signatories | Document verification and Internal review |
| 6. Signing mandate | Internal review and Approval |
| 7. Lipa Na M-PESA short code | Internal review |
| 8. Board resolution | Document verification and Approval |
| 9. Documents and review | Document verification |
The pattern is clear: the early steps establish identity and intent, the compliance step drives screening, and the later steps supply the documentary and authorisation evidence that verification and approval depend on. A gap at any step surfaces at the corresponding stage rather than at the end.
Compliance and screening as a gate, not an afterthought
The compliance check is the stage most likely to halt an application, and it is also the one banks are most accountable for under the Central Bank of Kenya's prudential expectations on account opening and KYC, and the Financial Reporting Centre's AML obligations. Creodata BAOS captures the PEP and FATCA declarations inside the application and works out every person who needs screening — directors, beneficial owners, signatories — once each, listing them on the application for your compliance team; the screening itself runs in your screening tool, and the decision stays with your staff.
This is the point at which onboarding connects to the bank's wider financial-crime programme. Screening at account opening is the first control; ongoing monitoring after the account is live is a separate discipline. For the screening logic itself, see PEP and sanctions screening at account opening and the cross-cluster explainer on sanctions and PEP screening. Where an entity's ownership is layered or opaque, beneficial ownership and entity resolution describes how that knot is untangled. BAOS does not search sanctions or PEP lists itself and is not tied to any screening vendor: it tells your compliance team who to screen, and the bank chooses the tool that does the screening.
Documents, signatories, and authorisation
Most of the delay in corporate onboarding sits in three places: documents that are missing or wrong, signatory details that do not match the mandate, and a board resolution that does not actually authorise what the applicant has requested. The wizard front-loads all three. The checklist-driven upload in step 9 means a bank can configure exactly which documents it requires; staff verify them one at a time or a whole application at once, and the files are stored in Azure Blob Storage (MinIO in the on-premises design).
Because signatories (step 5), the mandate (step 6), and the board resolution (step 8) are captured as structured data rather than free text, a reviewer can check them against each other: that the number of required signatories matches the operating instruction, and that the people named in the resolution are the people authorised to act. This structured capture is what makes the audit-ready onboarding trail possible — every decision is attributable to the reviewer who made it, with their comments. The wider audit-ready, four-eyes principle is covered in the AML cluster.
Turnaround, the handoff, and what happens next
The final two stages — approval and account creation — are where the applicant finally sees a result. Approval is a deliberate decision recorded against the application; account creation happens in the bank's core systems. Creodata BAOS does not book the account in your core banking system: staff open it there and record the account number in BAOS. A direct integration would be a separate project, so the onboarding system is not tied to any one core-banking platform.
Turnaround is tracked by SLA timers on the workflow steps, with a dashboard of average time per step that shows operations teams where applications spend their time. The discipline of measuring and managing that time is covered in account opening turnaround time and SLAs, and the related problem of applicants giving up midway is the subject of reducing account opening abandonment. Once the account is open, the customer relationship moves from onboarding into ongoing monitoring — the domain of the Creodata AML Compliance Platform.
Frequently asked questions
How long does the corporate account opening process take?
There is no single fixed duration, because turnaround depends on the completeness of the application and the bank's own SLA targets. What Creodata BAOS provides is visibility: SLA timers run on the workflow steps and a dashboard shows average time per step, so operations teams can see where applications spend their time. Applications that arrive complete — correct documents, clear mandate, disclosed stakeholders — move through verification and review faster than those that need rework.
What is the difference between the applicant steps and the bank workflow?
The applicant completes a nine-step wizard that captures business information, account choices, compliance declarations, signatories, the signing mandate, any M-PESA short code, the board resolution, and supporting documents. Most banks then run that submission through a separate six-stage workflow — Submission, Compliance check, Document verification, Internal review, Approval, and Account creation; in BAOS, a reviewer claims the application, verifies documents and approves or rejects it, and staff record the account number once the core banking system opens the account. The two are linked but distinct: several applicant steps feed a single workflow stage, and some stages, such as internal review, draw on the whole application at once.
Can an applicant save a corporate application and finish it later?
Yes. The wizard auto-saves to draft between steps, so an applicant can leave an incomplete application and resume it from the customer self-service portal at any point. They sign in, continue where they left off, and track the status of submitted applications through a non-enumerable reference token rather than a sequential number, which avoids exposing one applicant's reference to enumeration by another.
To see the full nine-step wizard and the staff review workflow in operation, read about the Creodata Bank Account Opening System or book a demo to walk a live corporate application from business information through to the recorded account number.